 By
Safaricom has won a place in the legal fight over the Communications Authority of Kenya's (CA) revised spectrum fees, bringing the country's largest operator into a dispute that Jamii Telecommunications (Faiba) opened in 2025. The outcome will shape how every network operator pays for the radio frequencies behind mobile data, 5G and wireless home internet, and it will influence how much of that cost reaches consumers and businesses.
Justice John Anuro of the High Court allowed Safaricom to join the proceedings, according to a ruling reported on 28 October. The CA's revised schedule has been suspended since 24 April 2025, so the fight is not yet about collecting the new charges. It is about whether the pricing system should stand at all.
What the High Court decided, and what it did not
The Communications and Multimedia Appeals Tribunal had earlier turned Safaricom away. It found that the company had not explained what harm it would suffer if excluded, and it noted that Safaricom had not said whether it supported or opposed Jamii's appeal. The CA opposed Safaricom's entry, arguing that the operator had not attached material setting out its case and warning that admitting it could prejudice the Authority's response. Jamii did not oppose the application.
The judge found that the tribunal had applied the test for admitting an interested party too rigidly. Safaricom's affidavit said the outcome could affect its regulatory obligations, financial outlay, business planning and competitive position, and the court treated that as enough, even if it lacked detail. The judge also rejected the idea that Safaricom had to pick a side before being admitted. An interested party, he said, can back some arguments, oppose others, or simply explain how the result affects it.
The ruling carries limits. Safaricom must confine its submissions to the issues Jamii has already raised. It cannot add a new claim, ground of appeal or remedy, and it cannot take control of the case. The tribunal is expected to set timelines for Safaricom's affidavit and submissions. Tribunal proceedings had been paused since 19 September 2025 while Safaricom's appeal was pending.
The court record reported so far does not show Safaricom taking Jamii's side. The operator has said it wants to explain how the fee framework affects its own position and to offer technical and economic context. Whether it ends up supporting Jamii, opposing it or landing somewhere between is not yet known.
How the fee model is changing
Until now, spectrum charges have followed a formula in the CA's schedule that took effect on 1 July 2018. According to a draft market review prepared for the CA and the ICT Authority, it combines a fee for exclusive use of a specific bandwidth with a usage fee that depends on the number of transmitters in an operator's network.
The CA announced in May 2024 that it would issue new frequency prices, the first review since 2018, following a study by Advatech Group and LS telcom that began in September 2023. The proposed model sorts spectrum into low, medium and high bands instead of pricing mainly by transmitter count. On 10 March 2025, the Authority told licence holders that revised annual fees would apply from 1 July 2025. Jamii challenged the schedule, arguing that it favours dominant operators with greater resources and revenue share, and calling it "discriminatory, uncompetitive, unfair, unsustainable, and unreasonable." It also argued that public consultation was superficial. The CA says the review reflects inflation, technological change, efficient use of spectrum and the need to support investment and connectivity.
They described the change as an increase. The per-band rates and the size of the rise were not set out in the court coverage or in the draft review examined for this report, which limits how precisely the impact can be measured.
Previous approach (2018 schedule) | Revised approach (suspended) | |
|---|---|---|
Basis of charge | Exclusive bandwidth fee plus a usage fee tied to transmitter count | Band-based charge tied to the amount of spectrum assigned |
Fee moves with network size | Yes | No |
Stated policy aim | Cost recovery and spectrum management | Account for inflation and technology, encourage efficient use, support investment |
Why Jamii, and why now
Jamii's history with the regulator explains some of the friction. It received 700 MHz spectrum on a trial basis in 2017, a move that Safaricom and Telkom objected to at the time, and it was awarded a full licence in 2019 with permission to pay its KSh2.5 billion licence fee in instalments over 10 years, according to Connecting Africa and the draft market review. In the CA's data, Jamii held about 1.2 percent of mobile data subscriptions in the 2024/25 financial year, against 65.1 percent for Safaricom. In fixed internet, however, Jamii is a major player: it reported 541,003 subscriptions at the end of June 2026, or 19.1 percent of a market of 2.84 million, behind Safaricom's 1,024,950 (36.1 percent), according to CA statistics.
Complaints about spectrum costs are not new among the larger operators either. In 2020, Safaricom and Airtel both wrote to the CA arguing that fees were too high and that they limited cheaper services . Airtel argued at the time against setting fees to maximise revenue.
Analysis: what the economics suggest
A fee on the airwaves versus a fee on the network
The CA's own consultants identified the central design problem. A per-transmitter fee rises as an operator builds more sites, which reduces the incentive to expand, including into under-served areas. The draft review says that moving away from that basis could raise fees for operators with smaller networks, and it warns that any new regime must be competitively neutral so that smaller rivals are not squeezed out.
The logic follows from simple arithmetic. A band-based fee does not increase when a site is added, so an operator with a large, dense network spreads one charge over many more customers. Safaricom had 61.4 million active lines at the end of June 2026, roughly 70 percent of a market of 88 million lines, according to CA data. An operator with a few hundred thousand users pays the same rate per MHz but recovers it from far fewer people. If low bands, which carry coverage, are priced above high bands, a smaller operator holding sub-GHz spectrum such as Jamii's 700 MHz block could face a bill that grows faster than its revenue. That is a mechanism the schedule permits, not a documented outcome, since the rates have not been published in the material reviewed.
5G rollout
Kenya's 5G base remains small but is growing quickly. CA statistics for April to June 2026, as summarised by one Nairobi-based analyst, put 5G subscriptions at 2,103,217, up 68.6 percent from 1,247,713 a year earlier. The GSMA projection cited in the draft review has 5G connections rising from 2.8 million in 2025 to 19.8 million in 2030, with population coverage reaching 99 percent. Reaching that coverage requires spectrum, site densification and fibre, the review says.
Given that trajectory, a fee that no longer scales with each new transmitter should favour operators that are already building out 5G. Safaricom launched commercial 5G in October 2022 using a 60 MHz block in the 2600 MHz band, and Airtel followed in mid-2023. For a smaller operator, the same change could make a 5G or high-capacity build harder to justify, because the cost of holding the spectrum arrives before the revenue from the sites that use it. The likely result is that the fee structure widens the gap between operators able to fill their spectrum with traffic and those that cannot.
Fixed wireless access: where margins are thinnest
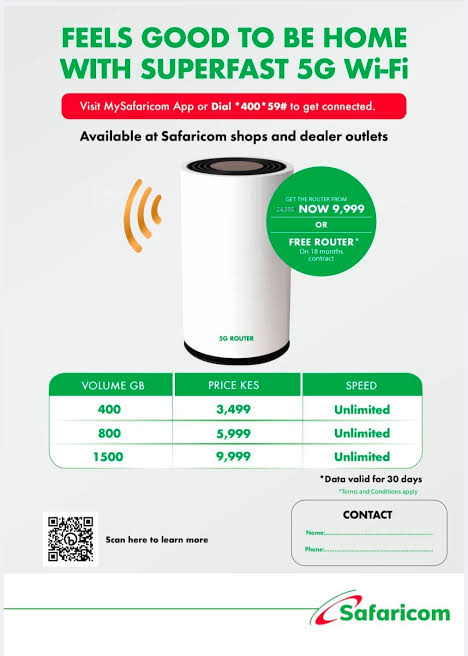
Fixed wireless access (FWA) is the segment where the fee design bites hardest. A household on a fixed wireless plan consumes far more capacity than a phone user, so spectrum cost per customer rises with usage even when the annual fee is fixed. Safaricom's 5G for Home plan starts at KSh4,000 a month for 50 Mbps with a 1.5 TB allowance, and the company's 5G router customers grew 53 percent in the year to March to 132,060, accounting for 52.3 percent of its net growth in fixed lines.
The pricing context matters here. The draft review, using ITU data, shows Kenya's 5 GB mobile data basket at USD 7.73 against USD 23.19 for a fixed broadband basket of the same size, and it notes that fixed prices appear high. FWA is one of the ways operators can close that gap. Any change in spectrum cost therefore lands on a product that is meant to undercut fibre and compete with it. Jamii, which competes with Safaricom across fixed connections, has a direct commercial reason to care how that cost is calculated.
Retail data prices and enterprise connectivity
Spectrum cost is not a minor line item in Kenya. The draft review says that in confidential data submitted by operators, spectrum accounts for 18 to 24 percent of operating costs, compared with 2 to 3 percent in a stylised cost model developed for South Africa's regulator. The operators behind the Kenyan figures are not identified. If that range is representative, a given percentage change in spectrum fees would move unit costs more than it would in markets where the item is small.
Whether that reaches customers depends on market structure. The review calculates a Herfindahl-Hirschman Index of 5,252.5 for mobile data subscriptions, a level it classes as highly concentrated, and puts Safaricom's share of mobile revenue at 83.4 percent in 2024/25. In a market like that, the dominant operator has more room to absorb a cost change, while smaller operators have less room to pass one on, because they price in the shadow of the leader. For enterprise connectivity the same pressure applies to a wider group. The CA's licensing data shows 4 Tier 1, 39 Tier 2 and 149 Tier 3 network facilities providers, and many of them sell leased lines, wireless links and backhaul to businesses on thin margins. Their sensitivity to a fee that does not scale with network size is likely to be higher than that of the national operators.
The counterargument
The CA's case is not weak. The last schedule dates from 2018, and a fee set that long ago does not reflect inflation or the economics of 5G-era bands. Charging by amount of spectrum assigned is also a common regulatory approach. Ofcom, for instance, prices annual licence fees per MHz and in July 2025 reduced the charge for the 900 MHz and 1800 MHz bands by 26 percent while raising it by 6 percent for 2100 MHz.
South Africa's regulator sets a unit price per MHz of paired spectrum that it adjusts each year for inflation, at R3,367 from April 2026, according to a South African law firm's summary of ICASA's fee schedule. A per-MHz charge can also discourage operators from holding spectrum they do not use, which matters in a market where frequencies are scarce.
There is a further argument that cuts against Jamii's framing. In a 2021 petition to Parliament, Airtel said it held 50 MHz against Safaricom's 82.5 MHz and Telkom's 37.5 MHz, and argued that the dominant operator held excessive spectrum. Those holdings are dated, but if they remain broadly accurate, a charge based on the amount of spectrum assigned would fall most heavily in absolute terms on the largest holder. On that reading, the revised schedule would not simply favour dominant players.
Taken together, the evidence suggests the dispute turns less on whether spectrum should be priced by band and more on whether the rates are adjusted for footprint and use. Regulators elsewhere build in that kind of adjustment, such as the geographic factor in South Africa's fee regulations. The CA's draft review itself flags the risk of excluding smaller rivals, and the tribunal will have to decide whether the 2025 schedule managed it.
Comments